Is Buy Now, Pay Later (BNPL) Worth It in the Philippines? SPayLater, Lazada PayLater, GCredit & Maya Compared (2026 Guide)
Sulit verdict: It depends on which app, and whether you actually pay before the due date. Used as a genuine 0%-or-low-cost installment tool for a purchase you already planned to make, SPayLater, Lazada PayLater, GCredit, and Maya Easy Credit can be sulit. Used as a way to buy things you couldn’t otherwise afford, they’re some of the most expensive short-term credit in the country — the real rates below run higher than most credit cards. Read the terms in your own app before you tap “confirm,” because the numbers change by platform, by promo, and by how long you take to pay.
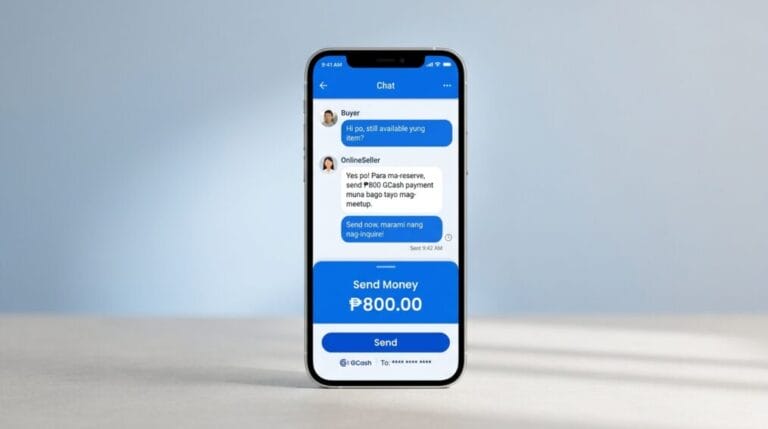
Buy Now, Pay Later (BNPL) has quietly become the default checkout option on Philippine e-commerce and e-wallet apps. Shopee, Lazada, GCash, and Maya each have their own version baked directly into checkout, which means the “pay in installments” button is often one tap away from your cart — no separate loan application, no waiting days for approval. That convenience is exactly why it’s worth understanding what you’re actually agreeing to before you tap it, especially during a big sale window like 9.9 or 11.11 when everyone’s cart total is bigger than usual.
This guide breaks down what each major BNPL option in the Philippines actually charges, what the government’s interest rate cap does and doesn’t cover, and how to tell a genuinely sulit 0% promo from a “free” installment that quietly isn’t.
What Counts as BNPL in the Philippines Right Now
“BNPL” isn’t one single product here — it’s a handful of different credit lines that show up as a payment option at checkout:
- SPayLater – Shopee’s built-in credit line, usable both on and off the Shopee app.
- Lazada PayLater – powered by CIMB Bank Philippines, available at Lazada checkout.
- GCredit – GCash’s revolving credit line, usable at partner merchants, bills payment, and QR checkout, not just online shopping.
- Maya Easy Credit – Maya’s credit line, drawn either into your Maya wallet or used directly at checkout.
- BillEase – a standalone BNPL provider accepted at specific online and retail partners (electronics stores, some telco and appliance brands).
All five are credit — you’re borrowing money the platform expects back, usually with a cost attached unless you qualify for a specific 0% promo. None of them are “free money,” even when the marketing on a sale banner makes it look that way.
What Each One Actually Charges
Here’s what each provider discloses on its own official fees pages, current as of this writing. Rates on BNPL products are typically risk-based, meaning your specific rate depends on your credit history with that platform — treat these as the disclosed ranges, not a guaranteed number for your account.
| Provider | Interest / Service Fee | Late Payment Fee | Typical Tenor |
|---|---|---|---|
| SPayLater | ~1% – 5% per month on the order, plus a processing fee that varies by promo | ~2.5% – 5% added monthly on the overdue amount | Pay-in-full next cycle, or 3/6/12-month installments |
| Lazada PayLater (CIMB) | 1.00% – 5.00% per month on the utilized limit, plus documentary stamp tax | 5% of the outstanding principal or ₱50, whichever is higher, per month | 1, 3, 6, 9, or 12 months |
| GCredit | 5% – 7% per month, charged daily from the day after you borrow (monthly rate ÷ 30) | Not separately disclosed on GCash’s public fees page – check your in-app disclosure statement | Revolving; interest stops once you repay |
| Maya Easy Credit | Service fee as low as 3.99% of the used limit, plus documentary stamp tax | Daily penalty on the overdue principal (rate shown in your personal disclosure statement) | Typically due within 30 days, or split into installments depending on the offer |
| BillEase | No processing fee on the Credit Line itself; interest applies on a declining balance if not paid in full | Delinquency interest plus possible collection fees if unpaid | Varies by merchant partner and plan selected |
Heads Up: None of these providers publish one single fixed rate that applies to every user — GCash, Maya, and CIMB (for Lazada PayLater) are all explicit that your actual rate depends on your account’s risk profile and is confirmed in your personal disclosure statement before you borrow. Always check that in-app number before confirming, not the general range above.
The Rate Cap You’ve Probably Never Heard Of — and Its Real Limits
The Securities and Exchange Commission (SEC), implementing Bangko Sentral ng Pilipinas (BSP) Circular No. 1133, put a ceiling on what lending and financing companies — including online lending platforms — can charge, effective March 3, 2022. Under SEC Memorandum Circular No. 3, Series of 2022, covered loans are capped at:
- A nominal interest rate of 6% per month (about 0.2% per day)
- An effective interest rate (which folds in processing, service, and other fees) of 15% per month (about 0.5% per day)
- Late payment penalties of up to 5% per month
- A total cost cap of 100% of the amount borrowed, across all interest, fees, and penalties combined, no matter how long the loan stays unpaid
Good to Know: This cap only applies to unsecured, general-purpose loans of ₱10,000 or less with a tenor of up to four months. That’s a meaningfully narrow slice of what BNPL apps actually offer — a ₱30,000 Lazada PayLater plan over 12 months, for example, sits outside that specific ceiling. Don’t assume every BNPL transaction is automatically capped just because the regulation exists; check whether your specific loan amount and tenor actually falls inside it.
Worked Scenario: Is It Actually “Free” If You Pay on Time?
Say you use GCredit to cover a ₱1,000 purchase and pay it off nine days later. Per GCash’s own published example, interest is calculated as the monthly rate divided by 30 days, times the number of days borrowed. At a 5% monthly rate: ₱1,000 × (5% ÷ 30) × 9 days = ₱15 in interest, for a total of ₱1,015 due. Pay it back the same day you borrowed, and GCash charges no interest at all — that’s the closest thing to genuinely free BNPL gets.
Now compare that to Maya Easy Credit’s own published example: borrow ₱10,000 and pay it back within the standard cycle, and the illustration on Maya’s own site shows a 3.99% service fee (₱399) plus documentary stamp tax (₱6.16), landing you at ₱10,405.16 due — before any late penalty. That’s the cost of convenience even when you’re not late, and it’s higher in peso terms than most people expect from a “just tap to pay” checkout option.
The pattern across all of these: the fee is small and easy to justify on any single purchase, but it’s still a real cost, and it compounds fast the moment you miss the due date — especially under GCredit’s daily accrual or Lazada PayLater’s 5%-or-₱50-per-month late fee.
When BNPL Is Actually Sulit — and When It’s a Debt Trap
BNPL tends to make sense when you already had the cash-equivalent budgeted for the purchase, you’re using it purely to smooth out timing (like spreading a laptop purchase across payday cycles instead of taking one lump hit), and you’re confident you’ll hit every due date without stretching your other bills to do it.
It becomes a problem the moment it’s used to buy something you couldn’t otherwise afford at all, or when someone stacks multiple BNPL lines (SPayLater plus GCredit plus a Lazada PayLater balance, for instance) without tracking the combined monthly due amount across apps. Because each provider only shows you your own balance, it’s easy to lose track of how much total debt you’re actually carrying across platforms during a heavy shopping month like the Ber-months.
Sulit Tip: Before you tap any BNPL option at checkout, ask yourself the same question you’d ask about a credit card installment: would I still buy this today if I had to pay the full amount up front, right now? If the honest answer is no, that’s the app telling you it’s a want stretched into a “yes,” not a need.
Also Worth Checking
If you’re weighing BNPL against other ways to finance a purchase, our breakdown of whether 0% credit card installment is actually free covers the card-based version of this same question, and our guide to online lending apps and the 2026 SEC rules digs deeper into the regulatory side for standalone loan apps. If your BNPL purchase is timed around a specific sale date, our Shopee, Lazada & TikTok Shop sale calendar maps out which dates are actually worth waiting for. For more of this kind of value-first breakdown, head back to more sulit finds.
Frequently Asked Questions
Is BNPL really free if I pay on time?
Sometimes, but not always. GCredit charges zero interest if you repay the same day you borrow, and some SPayLater or Lazada PayLater promos run genuine 0% campaigns on specific sale dates. Outside of those specific conditions, a service fee, interest charge, or documentary stamp tax typically applies even when you pay on schedule — check your in-app disclosure statement before confirming.
Does using BNPL affect my credit standing in the Philippines?
BNPL providers here are lending or financing companies (or bank-partnered products, in Lazada PayLater’s case), and unpaid balances are treated as real debt that can affect your standing with that provider and, depending on the platform, your eligibility for future credit limit increases or other financial products.
What happens if I miss a BNPL due date?
Expect a late fee — a percentage of the overdue amount, charged monthly or daily depending on the provider — on top of continuing interest. Lazada PayLater, for example, charges 5% of the outstanding principal or ₱50 (whichever is higher) per missed monthly payment.
Is BNPL interest capped by law?
Only within a specific range: unsecured loans of ₱10,000 or less with a tenor of four months or less are capped under SEC Memorandum Circular No. 3, Series of 2022. Larger amounts or longer tenors — common on Lazada PayLater’s 6-12 month plans, for instance — fall outside that specific ceiling.
Which BNPL option is cheapest?
There’s no single answer — it depends on your personal disclosed rate, the tenor you choose, and whether a 0% promo applies to your specific purchase. GCredit’s same-day repayment is the closest thing to guaranteed-free; beyond that, compare the actual percentage shown in your app before choosing, rather than assuming one platform is always cheaper.
Verified Sources Used
GCash Help Center: Confirmed GCredit’s 5%–7% monthly interest range, daily accrual method, and the same-day-repayment interest waiver.
Shopee Philippines (official blog): Confirmed SPayLater’s interest range, processing fee range, and available 1/3/6/12-month tenors.
CIMB Bank Philippines – Lazada PayLater Product Disclosure Sheet: Confirmed Lazada PayLater’s 1%–5% monthly interest, late payment fee structure, documentary stamp tax, and available tenors.
Maya Digital Bank (official): Confirmed Maya Easy Credit’s service fee structure, documentary stamp tax, and the ₱10,000 worked example used above.
BillEase (official FAQ): Confirmed BillEase’s no-processing-fee Credit Line structure and declining-balance interest on merchant loans.
Securities and Exchange Commission (SEC), Philippines: Confirmed the interest rate cap, effective interest rate cap, penalty cap, total cost cap, loan-amount/tenor threshold, and effective date under SEC Memorandum Circular No. 3, Series of 2022, implementing BSP Circular No. 1133.